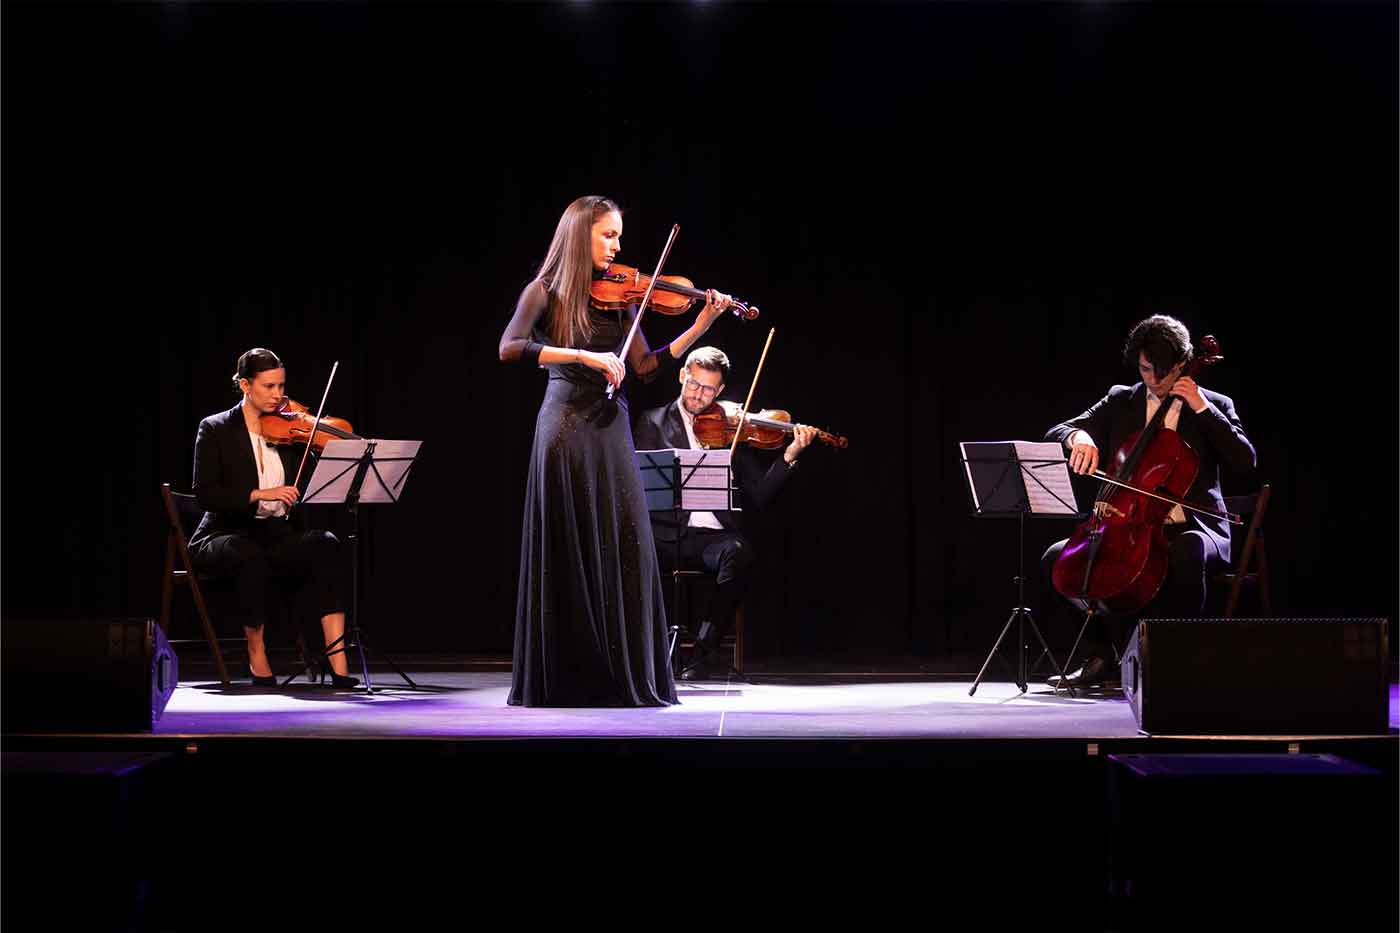
Recent legal reforms have significantly improved funding for the cultural sector. Today, theatrical, musical, and audiovisual productions can benefit from tax incentives that promote their development and dissemination and have a significant positive impact on society.
The Role of Tax Incentives in the Cultural Sector
These measures not only ease the tax burden on those who support cultural projects but also open up new funding channels for producers, making the system beneficial for promoters, creators, and investors alike.
Access to funding remains one of the main challenges for those involved in producing cultural projects. In recent years, tax regulations have incorporated measures that partially alleviate this obstacle, opening up new possibilities for certain projects to access other sources of funding with the greatest possible legal safeguards.
Evolution of the Legal Framework
Currently, various types of cultural productions—such as audiovisual works, plays, concerts, and dance performances—can benefit from a system that recognizes the right to claim tax deductions against corporate income tax. Producers may claim these deductions themselves or, under certain conditions, transfer them to third parties interested in participating in the project—that is, to investors.
The audiovisual sector has traditionally enjoyed the most favorable tax treatment, as the first specific incentives were introduced in 1995, although they were limited and unattractive measures. They were consolidated following substantial changes to the regulations in 2015 with the corporate income tax reform, which established an attractive framework for domestic and international productions. In recent years, this favorable treatment has gradually been extended to other disciplines, such as the performing arts and live music, which did not have their own tax regime until 2015, when a specific deduction was introduced for the first time. Although differences in scope and rates still persist across sectors, the regulations have evolved toward a broader and more inclusive approach to cultural activities as a whole.
Benefits for Producers and Investors
For many filmmakers, these film tax incentives have provided an additional source of funding, making it possible to carry out projects that would otherwise be more difficult to bring to fruition, thereby contributing significantly to the industry's development.
As we previously announced, tax regulations also provide benefits for those who choose to contribute funds to cultural projects carried out by third parties; under certain conditions, these benefits may be available to private investors.
This model allows companies and professionals to contribute to cultural development while potentially qualifying for a corporate income tax deduction or, in some cases, a personal income tax deduction. These are not subsidies, but rather a system that channels a portion of tax revenue toward cultural activities with social and economic impact.
Challenges in Cultural Policy
Investor participation in these types of initiatives has increased in recent years, driven by regulatory clarity and the appeal of combining a cultural purpose with tax optimization.
Although there are still many areas for improvement—such as ensuring equal tax treatment across different disciplines and models—the current framework offers an increasing number of tools that can contribute significantly to access to, production of, and preservation of culture in its many forms.
Inés de Casas, Senior Associate in the Media & Entertainment Practice